Renewable Energy & InfrastructureMarket analysis
Renewable energy investment: Gulf solar, UK offshore wind and how private investors take part
Dubai's solar park has reached 3,860 MW, the UK's January 2026 auction awarded about 8.4 GW of offshore wind, and Saudi Arabia targets about half its electricity from renewables by 2030. Why most investors take part through listed companies and funds.
- Author
- Bee Haven International
- Published
- Updated
- Facts verified
- Reading time
- 2 min read
 Pakistan
 United Arab Emirates
 United Kingdom
 Saudi Arabia
 Oman
 United States
Executive summary
Large renewable projects are tendered to experienced consortia under long-term contracts: Saudi Arabia buys power through a single buyer, Dubai's DEWA runs a solar park that has reached 3,860 MW, and the UK's Contracts for Difference Allocation Round 7 awarded about 8.4 GW of offshore wind in January 2026 at £91.20/MWh for fixed-bottom projects in England and Wales (2024 prices). Private investors usually take part through listed utilities, renewable investment trusts, funds or green bonds. In the US, infrastructure projects can qualify for EB-5 at US$800,000. Risks include construction, policy changes, power prices and interest rates.
Key findings
- Saudi Arabia aims for about half its electricity from renewables by 2030; projects tendered as IPPs with long-term purchase agreements.
- UAE: target to triple renewable capacity to 14 GW by 2030; DEWA's solar park at 3,860 MW, planned to exceed 8,000 MW.
- UK AR7 (January 2026): about 8.4 GW of offshore wind; £91.20/MWh for fixed-bottom offshore wind in England and Wales (2024 prices).
- Oman: 30% renewables by 2030 and green-hydrogen land blocks allocated by Hydrom.
- US: EB-5 infrastructure projects at US$800,000; 2% of EB-5 visas reserved for infrastructure.
Key figures
- UK AR7 offshore wind awarded
- ≈8.4 GW
- January 2026 · DESNZ
- Dubai solar park capacity
- 3,860 MW
- 2026 · DEWA
- UAE renewable target
- 14 GW by 2030
- UAE Energy Strategy 2050 · UAE Embassy in Washington
Governments across our markets are building renewable capacity at record pace. For most private investors, though, the opportunity is indirect: the projects themselves are tendered to large consortia.
Where the capacity is being built
- Saudi Arabia. The National Renewable Energy Program aims for about half of electricity from renewables by 2030. Projects are tendered as independent power producers with long-term purchase agreements; the Saudi Power Procurement Company is the single buyer.
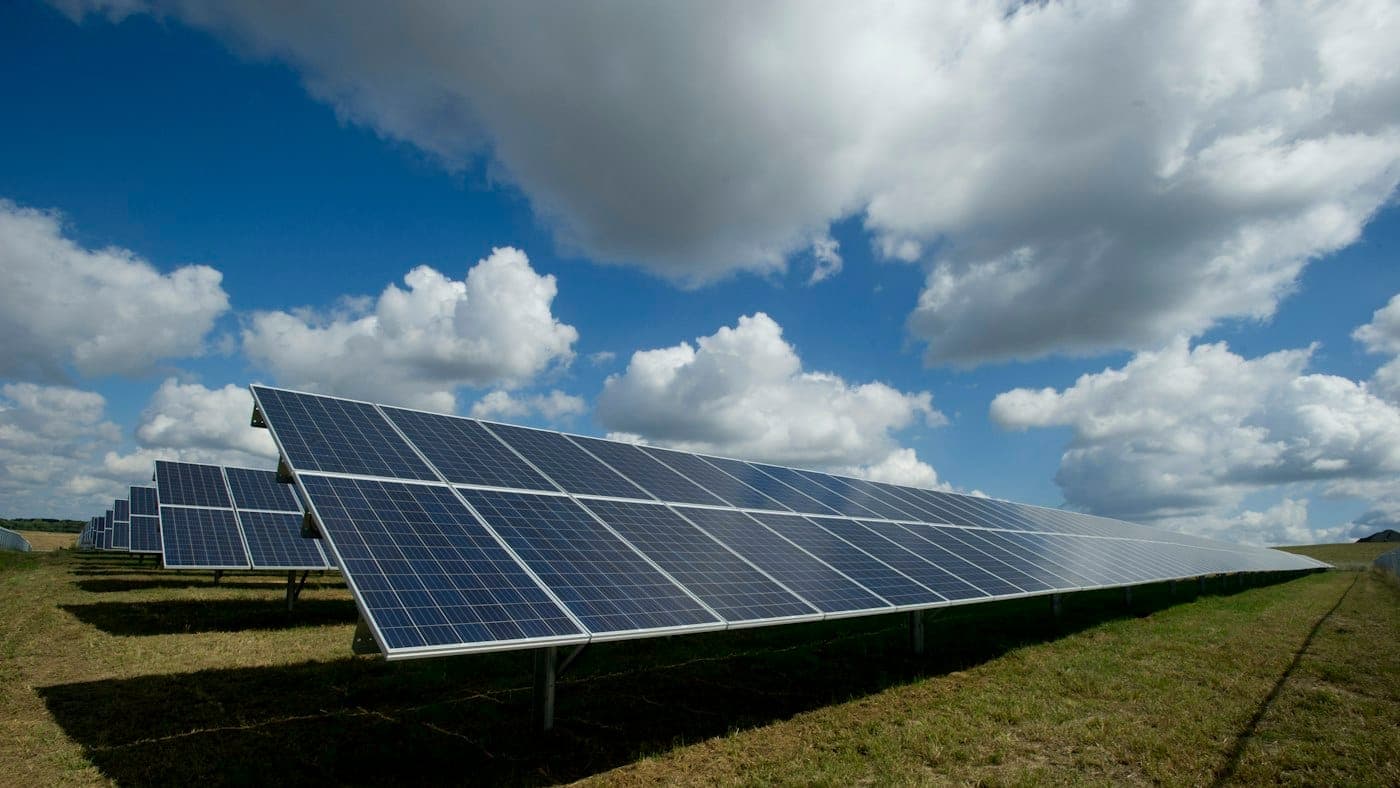
- UAE. The Energy Strategy 2050 aims to triple renewable capacity to 14 GW by 2030. DEWA's Mohammed bin Rashid Al Maktoum Solar Park has reached 3,860 MW and is planned to exceed 8,000 MW by 2030.
- United Kingdom. Contracts for Difference Allocation Round 7 (January 2026) awarded about 8.4 GW of offshore wind. Fixed-bottom offshore wind in England and Wales won contracts at £91.20/MWh (2024 prices). Projects receive a top-up to that strike price from the Low Carbon Contracts Company.
- Oman targets 30% of electricity from renewables by 2030 and allocates green-hydrogen land blocks through Hydrom.
- Pakistan lists renewable energy as a priority sector for foreign investors. Grid-connected projects sell to the Central Power Purchasing Agency.
- United States has no single federal target; many states set renewable portfolio standards. Federal clean-energy tax credits changed in 2025 — check the current rules for any project.
How private investors take part
| Route | What you own | Main points |
|---|---|---|
| Listed utilities and developers | Shares | Liquid; exposed to the whole company, not one project |
| Renewable and infrastructure investment trusts (e.g. London-listed) | Shares in a portfolio of operating assets | Can trade below asset value when interest rates rise |
| Funds and green bonds | Units or bonds | Diversified; check fees and what is actually "green" |
| Project equity | A stake in a project | Usually for institutions; illiquid for decades |
| EB-5 infrastructure (US) | An at-risk investment of US$800,000 | Green card route; must create 10 full-time jobs; capital not guaranteed |
Risks
- Construction: delays and cost overruns.
- Policy and subsidies: support schemes and tax credits change.
- Power prices: projects without fixed contracts are exposed to market prices.
- Interest rates: long-dated assets lose value when rates rise.
- Payment risk: in Pakistan, payment delays in the power sector (circular debt) have affected generators.
- Technology and weather, and early-stage industries such as green hydrogen, where timelines and buyers are uncertain.
Read our guide to renewable energy and infrastructure.
Sources
The official and named sources behind the facts in this article, with the date we last checked each one.
- 1.Contracts for Difference Allocation Round 7 results (opens in a new tab)
Department for Energy Security and Net Zero (UK) · January 2026 · checked 24 Oct 2026
- 2.Mohammed bin Rashid Al Maktoum Solar Park (opens in a new tab)
Dubai Electricity and Water Authority (DEWA) · checked 24 Oct 2026
- 3.UAE energy diversification (opens in a new tab)
UAE Embassy in Washington · checked 24 Oct 2026
- 4.Saudi Arabia's renewable energy deployment and 2030 targets (opens in a new tab)
Climate Scorecard · checked 24 Oct 2026
- 5.Oman: renewable energy (opens in a new tab)
US International Trade Administration · checked 24 Oct 2026
- 6.About the EB-5 visa classification (opens in a new tab)
USCIS · checked 24 Oct 2026
- 7.Long Term Residency (opens in a new tab)
Board of Investment (Pakistan) · checked 19 Oct 2026
Market analysis
This is general market analysis, not a recommendation to buy or sell any investment. Past performance is not a guide to future returns. Information on this website is general guidance only. Investment values can rise or fall, immigration rules can change, and eligibility depends on individual circumstances and decisions by the relevant authorities. Please obtain independent legal, tax, immigration and financial advice.